Showing posts with label real estate. Show all posts

Monday, November 12, 2018

October 2018 Ohio Housing Market Report

The

Ohio's October Housing Report: Tight inventory levels pushing list prices higher and shortening market times

Nov 8, 2018
The latest review of the Ohio housing marketplace shows a continued rise in list prices and fewer days homes are being marketed compared to October 2017. While the Buckeye State is continuing to confront the challenges posed by persistent low inventory levels of homes listed for sale, signs of improvement in select marketplaces are beginning to emerge.
Nationally, the takeaway headline from realtor.com's October 2018 Housing Report, which tracks inventory of for-sale single-family homes and condos, median list prices, inventory levels and days on the market for cities across the country, is that during the month there has been an uptick in the the inventory of homes listed for sale, combined with a continued rise in prices and decreases in time spent on the market.
“Ohio is continuing to face the challenge of low levels of homes currently listed for sale, although there are signs of improvements in some of our marketplaces,” said Ohio REALTORS President Tiffany Meyer. “The tight inventory of homes for sale is not only contributing the list prices continuing to tick upward, it is a key factor in quickening the pace of sales in nearly every market throughout the state."

Ohio Housing Report -- October 2018 vs. October 2017
Ohio MarketplaceMedian List PriceDays on MarketActive Listings
Akron$160K / 7%58 / -3%2.6K / -11%
Ashtabula$120K / 9%79 / -4%475 / -3%
Canton-Massillon$147K / 7%48 / -10%1.3K / -9%
Chillicothe$135K / -4%61 / -8%274 / -21%
Cincinnati$240K / 13%53 / -5%7.3K / -3%
Cleveland-Elyria$180K / 9%65 / -6%8.7K / -6%
Columbus$240K / 0%46 / -10%7.7K / 54%
Dayton$143K / 4%52 / -13%3.8K / -6%
Findlay$180K / 6%64 / -1%322 / 3%
Lima$123K / 17%69 / -1%405 / -14%
Mansfield$123K / 6%53 / 4%361 / -16%
Marietta$160K / 0%74 / -9%165 / -17%
New Philadelphia-Dover$144K / 11%56 / -27%260 / -10%
Portsmouth$110K / -5%88 / -8%343 / 0%
Salem$121K / 5%81 / -14%424 / -9%
Sandusky$189K / 5%84 / -7%619 / -13%
Springfield$113K / 3%59 / -14%762 / 4%
Steubenville-Weirton, WV$95K / 6%76 / -17%437 / -20%
Toledo$139K / 7%60 / -6%2.5K / -3%
Wooster$165K / 14%58 / -5%306 / 19%
Youngstown-Warren-Boardman$120K / 11%70 / -13%2.4K / -10%
Zanesville$156K / 4%70 / -5%474 / 10%
U.S. Average$295K / 7%68 / -7%1.6M / 2%

Sunday, April 8, 2018

Top Ten Things Agents Do That Sellers Love

We know sellers need agents. In fact, 89 percent of sellers list with one. But how do sellers rank agent services in order of importance? We analyzed the data in the Zillow Group Consumer Housing Trends Report 2017 and found sellers most valued when agents:

10)  Stage the home

9)   Arrange video and other media to showcase the home

8)   Provide legal advice

7)   Hold open houses and private tours

6)   Determine the home’s list price

5)   Promote listing on real estate sites

4)   Arrange for photographs to be taken of the house

3)   Lead contract negotiations

2)   Give guidance on the overall selling process

Most importantly … 

1)   Find interested buyers

The Zillow Group Consumer Housing Trends Report 2017 has even more ideas on how you can help your sellers during such a stressful time in their lives. Take a look to learn more about buyers and sellers, and how you can shape their experience.

5 Housing Market Trends that are Changing the Market Today

Wednesday, October 19, 2016

First-time Home Buyer Process Guide

The internet is covered in high quality information aimed at helping first time home buyers understand the process of getting a house. However, there is one small problem. There are a LOT of steps involved in buying a home. Most of the articles and videos that are available deal with one, two or may be three parts of the process. While this article could not possibly contain every scenario about getting a mortgage and finding a home, it will touch on the main points that are common to nearly every home purchase.

FIRST: GET PRE-APPROVED

Buying a home is a wonderful investment, but it should be approached with the right strategy. BEFORE finding a home, and falling madly in love with a neighborhood, people should first talk to a mortgage loan officer to get pre-approved vs pre-qualified.
It’s Best for the Buyer
Getting pre-approved gives the buyer a chance to find out how much home they can afford. A competent loan officer will tell the buyer not only the principal and interest payments per month, but also the estimated taxes, insurance and mortgage insurance monthly amounts. This gives the borrower a true number to work with in order to decide their comfort zone when looking at potential properties.
It’s Best for the Realtor
Once the buyer is pre-approved they can contact a real estate agent and start looking for a home. Agents have the ability to search for a home based on a number of criteria. Some of the items can be number of bedrooms, number of baths, square footage, location and total price. Incorporating the maximum price along with the other criteria can eliminate homes outside of the buyer’s criteria.
Many people think that getting pre-approved for a mortgage loan is just as simple as a car loan. However, nothing could be further from the truth. A mortgage is a very detailed loan that requires a number of documents and the correct procedures in order to complete the entire process. It all starts with the loan application.

LOAN APPLICATION

The first step in getting a home, and possibly the most important step, is the application.
The application is a lengthy form completed by the loan officer on behalf of the borrower. This form actually covers the potential homeowner’s entire financial situation in amazing detail.
For starters, people are asked for their name, social security number, date of birth, current address and current place of employment. If the application is for the purchase of a home an address of the new home will be requested. However, it is not crucial if a new home has not been picked out yet. The loan officer can continue with the application with an assumed address and change it later if necessary.
It is important to note that all borrowers need to show at least two year’s history for their residence and employment.
Next, the borrower will be asked about their assets. The term assets is a very broad term and can include a whole host of items such as
  • any available money in checking accounts
  • most recent savings account balances
  • stock and bond investments
  • land ownership
  • any rental properties
  • retirement accounts such as 401-k or IRA accounts
  • income from ownership in businesses
Finally, the application will provide an estimate of the amount financed, the estimated closing costs, prepaid items and any money that the borrower will need to pay at the closing.
It cannot be stressed enough that the borrower needs to provide as much accurate detail about their income, assets and employment history. Making sure this information is up to date and correct will make the approval and underwriting process much easier.

PROCESSING THE APPLICATION

Processing is a broad term that covers a lot of ground. Once the loan officer has completed the loan application with the borrower and determined a price range for the home purchase, the borrower (or borrowers) have work to do. It is at this time that the borrowers will gather all the necessary documentation to qualify for the loan. People who receive a paycheck and a W-2 will likely need the following list of items:
  • Pay stubs covering the past 60 days
  • Bank statements (checking and savings) covering the past 60 days
  • Past two year’s W-2 forms from all jobs
  • Most recent statement from retirement and/or investment accounts.
The list of items for self-employed individuals is slightly different. They will need these items:
  • the last 2 years’ tax returns for their business
  • the last 2 years’ personal tax returns
  • cash flow statement for the current year
  • Personal bank statements (checking and savings) covering the past 60 days
  • Most recent statement from retirement and/or investment accounts.
The loan officer will have the borrower sign several documents such as the full loan application, the Good Faith estimate, the Truth in Lending and a few more forms. The processor will go over these documents, along with the financial documents mentioned above and make sure everything is in order. Once everything is signed and collected the processor will order the appraisal and the title insurance binder.
The appraisal is used to compare the home under contract with three or more other similar homes that have sold within the last 6 months. All comparable homes will usually be similar in design, square footage, general features and most importantly the location. The appraisal is used to determine the actual value of the home that the borrower wishes to buy.
The title insurance binder is protection for the buyer and the lender that the deed of record is correct before the home is sold. It also ensures that the new deed reflecting the new owners will be properly recorded after the sale.
Once the appraisal is complete and the title insurance binder is accurate all of the previously mentioned documents are combined and sent to the underwriting department.

DIFFERENT TYPES OF MORTGAGES

It is assumed in this country that any reasonably intelligent adult understands the basic points of a mortgage before purchasing a home. However, lots of people don’t know how to change the oil in a car they own. Likewise, millions of people own computers and have no idea how to fix some of the most common problems. For this reason, we want to explain the basics of the common types of mortgages.
Conventional – This is one of the most common types of mortgage loans available. It usually requires excellent credit scores (typically 700 and above) and a down payment of at least 3-5% of the purchase price. The conventional mortgage will usually offer the absolute best interest rate and payment compared to other programs.
FHA Loans – Authorized by the Federal Housing Authority (FHA) these loans are common for people buying their first home. The loan only requires a down payment of 3.5%* and the credit score requirements are less stringent compared to a conventional loan. FHA will allow the seller to pay up to 6% of the purchase price in closing costs to aid the buyer.
An added bonus is that the down payment can be a gift from a relative or friend. Another type of FHA loan, called FHA 203k loans, are also available if the house you are looking at needs rehab work done. The 203k loan allows borrowers to get the money needed for necessary repairs plus the price of the home and finance it all with one loan.
VA Loans – The Veterans Administration sanctions lending to veterans of the military. The VA loan does not require any down payment and also has lenient credit qualifications. In order to qualify for a VA mortgage loan a person will need to meet service criteria. The criteria vary based on active duty during war, reserve duty or duty served in the United States.
USDA Rural Housing – A division of the United States Department of Agriculture (USDA) provides home lending for properties in rural areas. No down payment is required if the appraised value of the home is high enough. For properties with a sufficiently high enough value, the closing costs can be added to the loan balance as well. The loan does have restrictions on income levels for the borrowers. Your loan office can compare your income to the USDA rules for your area and determine if you are eligible.
These are the primary types of loans available to the first time home buyer. Although the rates will vary from one loan to the next they are usually extremely close to each other. In order to decide which loan is best for your situation, you should consult with your loan officer.

THE MORTGAGE PAYMENT

Understanding a mortgage payment is very important for a first time home buyer. Most loans payments, such as for a car, are fairly simple to understand because it usually involves just two parts, the principal payment and the interest payment. However, that is not the case with the majority of mortgage loans.
Below is an example of what makes up a typical mortgage payment. We’ll assume there are escrows in place and mortgage insurance is required.
Mortgage Insurance
For this example, we will assume that your down payment is less than 20% of the home’s asking price. For conventional loans loans, any time a buyer pays less than 20% as a down payment; the borrower will be charged with mortgage insurance. This is an insurance protection to help the lender against any losses. The amount of the monthly mortgage insurance will depend on the type of loan, the borrower’s credit, the loan to value ratio, and the outstanding loan balance. The mortgage insurance is calculated as a percentage of the outstanding loan balance.
Homeowner’s Insurance One common practice for new home buyers is the use of an escrow account. This account is a holding place for the homeowner’s yearly homeowner’s insurance premium as well as the property taxes.
When a loan officer calculates the monthly mortgage payment they will usually add an amount to cover 1/12th of the annual homeowner's insurance policy.
Each time a mortgage payment is made some money is deposited into the escrow account. When the insurance premium comes due, money is removed from this account and directed to the insurance agent.
Property Taxes
Similar to the homeowner’s insurance, taxes are also accrued in the escrow account. When a person first buys the home, the taxes are pro-rated. The seller of the home pays the taxes for the part of the year in which they owned the home. This allows the new buyer to pay taxes only covering the time they actually owned the property.
Just like the homeowner's insurance, 1/12th of the annual property tax amount is added to the monthly mortgage payment. When the monthly payments are made part of the payment is put in the escrow account to cover the annual property tax bill.
Principal and Interest
This is similar to other loans. The interest amount is determined based on the stated interest rate for the mortgage, the term of the loan and the borrowed amount. Each month the amount of interest being paid goes down as the amount of principal goes up, reducing the outstanding balance a little more every month.

UNDERWRITING

The underwriter reviews the entire loan file. Everything from the income documentation, the asset documents, the appraisal and the title binder are all reviewed. Based on the type of loan that the borrower is seeking, the underwriter will compare the facts contained in the application and other documents against the guidelines and rules for that specific loan, plus any additional mortgage overlays.
The decision to approve the loan is guided by three principles
Credit – the borrower’s past credit history is a good indicator of whether or not the borrower has the intention of repaying the loan. Reviewing various types of loans, their duration and how the borrower handled each type of debt will show the underwriter if the borrower wishes to repay the loan.
Capacity – This is a mathematical computation to show that the borrower has enough income to pay for the loan. The underwriter will look at regular wages, overtime wages if the person has worked on the job for more than two years as well as commissions. All of this factors into determining the borrower’s capacity to pay any existing debt on top of a new mortgage.
Collateral– This is where the appraisal and title insurance come in. The underwriter will go through the appraisal to see that the home is being compared to very similar properties. The pictures of the homes are inspected to determine the pride of ownership of the previous owner and see if there are any problems. The title binder is studied to make sure there are no “unknown” liens preventing the borrower from taking over ownership of the property.
Because each type of mortgage has varying rules the underwriter will compare the borrower's information to the right guidelines for the loan. Consider the process of underwriting a loan in comparison to high school standardized tests. Standard tests are administered across the country to multiple grades. If a student scores at a certain reading level, then the person is awarded a particular grade level on their test. In other words, if the student's knowledge meets a particular minimum level, they are deemed to be at or above their grade level. A mortgage underwriter does a similar function comparing a person's credit, income and work history to the loan guidelines.
Once the underwriter has determined that all rules are being followed according to the lender’s policies the loan will be signed off and sent to the closing department.

CLOSING

Once the underwriting department has approved the loan and sent the file to closing a few more items are necessary. In the case that the homeowner is using an escrow service, an insurance policy and a property tax statement will be needed. The insurance policy is to replace the value of the home in case of fire, weather event or any other liability that may arise. The property tax statement provides the current year’s tax information so that the property taxes can be paid now and yearly going forward. An escrow service takes care of making the yearly insurance payment as well as the property taxes. The homeowner simply pays those amounts along with the monthly mortgage payment.
At the closing there will be either an attorney or the title company’s representative present to make sure of a few things. First and foremost is to properly identify the sellers and the buyers. This is usually done by getting a picture ID from each party. Secondly, many, if not all, of the documents must be notarized at the time of signing. Finally, the attorney or representative is there to explain all of the documents that will be signed by the borrowers and sellers. The outline of the amount being borrowed, the interest rate for the loan, the number of months for the loan and the monthly payment, including escrow, are all laid out in black and white for everyone to see.
There will be many forms to sign. Each form will be explained and you have the right to read over them and ask any questions. The representative or your loan officer will be able to answer any questions you may have.
Once all items are signed you will get a copy of everything to keep for your records. And then you will get something very precious: your set of keys!

SUMMING UP THE FIRST TIME HOME BUYER LOAN PROCESS

As you can see, there are quite a few details covered in the whole process of buying a home. However, if you are able to get your finances organized, promptly respond to requests from your loan officer, and have realistic expectations then you should experience a rather smooth process for buying a home.
Tuesday, August 30, 2016

5 Things Renters Should Know

5 Things Renters Should Know About Owning

For renters who aspire to be home owners, transitioning from an apartment to a house requires a shift in their thinking that they may not be prepared to make. The financial changes that come with owning, the need to consider planting longer-term roots in a neighborhood, and new neighborhood rules are things renters may not be thinking about enough.
As their real estate agent, it’s important for you to be there for your clients when they’re embarking on a life-changing event such as buying a home.
Moving can already be one of the most stressful times in a person’s life, but it may be doubly so for a new home owner. In order to be their most reliable resource, using your knowledge and experience to provide them with guidance, share these helpful nuggets of information with your clients so their transition from renter to owner can be as smooth as possible.
They need to understand how their financial investment is changing. Renters may see an increase in their monthly rent every lease term, but they don’t see exactly where it goes — toward property taxes and insurance, even “luxuries” such as trash pickup. As home owners, they don’t have a landlord who handles all those details, so they need to be ready to juggle the financial responsibilities of home ownership. Have an open conversation with your clients about these changes and the importance of budgeting to make sure they make smart financial decisions during this process.
They need to be happy with their location for the long-term. As a renter, you can bounce around from home to home every year if you want. But when you own a home, you have to stay put — unless you plan on renting it out, which most home owners don’t. Impress upon your client that location is going to play a much more significant role in their future, so they should think about evaluating school districts, access to amenities, and commute time now as they search for their next home.
They may need to abide by new rules. Renters don’t think about possible homeowner association rules they may be governed by, such as trash pickup rules or any curfews or rules pertaining to animals. Make sure to get all the information on neighborhood rules and associations to help your client understand what their new obligations will be.
They’ll need to get into the mindset of an owner. Life as your client knows it is about to change. Once your client purchases a new home, they will no longer have a landlord to tend to their many needs, including lawn care and plumbing. The best way you can help them as their real estate agent is to provide them with contact information for local industry experts. They will eventually need certified specialists ranging from HVAC companies to carpenters to electricians. Let them know they don’t have to do everything themselves.
They should know their neighbors can affect their value. Renters don’t care who their neighbors are as long as they’re quiet (enough). But your client is now going to want to know whether their new neighbors are renters or home owners. This knowledge can help your clients gauge current and future home value in the neighborhood. If the neighborhood consists mostly of rental properties, it is likely a home owner will lose money on their house in the future. Renters do not always feel responsible for maintaining their properties the way home owners do. Property value comes down to curb appeal. Less-appealing neighborhoods often have more-appealing prices, which is not always good for buyers and home owners.
Source: Rob Rimeris is owner of EverSafe Moving Co. in Philadelphia. EverSafe is a five-star, full-service company that offers affordable moving and storage services

Thursday, July 21, 2016

Location Location Location

Location? What Location?July 2016
Location? What Location? Which Location?!

It’s almost a joke these days, but one solidly mired in truth: the real estate mantra of location, location, location. It is of course the one thing about your new home that you can’t renovate or upgrade; that’s why considering exactly where you are buying is so crucial to your entire homeshopping experience.

So when you’re thinking about location, does it mean more than which city or town you want to live in? Of course it does. Here are four factors to consider when shopping for your new home, all related to location, location, location!
  1. Urban? Suburban? Rural? You can live in Chicago, or Tucson, or Sacramento without being downtown. Whether you want to be right in the city, on the outskirts, or more of a commuter makes a big difference in home prices and sizes, and in the time it will take you to get around.
  2. Narrowing it down. Once you know whether you’re a city kid or a country kid, you’ll need to drill down another layer and figure out what you want in the area directly surrounding your home. Do you want to be close to the freeway? Is it important to be able to walk to a coffeeshop, or to have a local farmers market, or ride your bike to the grocery store? Making a list of the features characterizing the neighborhood you dream of living in will help you find that neighborhood, so you can become part of it.
  3. Look up the future. By this, we mean check into plans for infrastructure updates, commercial zoning, and other planned developments in the area. Building on empty lots is good; having a freeway come through your backyard is not so good.
  4. The worst house on the best block. This is also an old saying that’s still totally true. If you can buy the worst house on the best block, it’s far better than buying the best house on the worst block. You can work toward getting your home in line with your neighbors’; there’s no guarantee your neighbors will try to catch up with you.
  5. Whether you’re looking to settle down to stay for years to come or you’re considering your new home’s resale potential, you’ll always need to put consideration of location at the top of your list of features you’re considering when shopping for your new home.
    If you’d like to discuss your homebuying options further, get started on a preapproval, or get a recommendation for a knowledgeable and respected agent in our area, it takes just a phone call or email and I can offer you my services. I look forward to working with you.
    Scott Melaragno
    Mortgage Loan Originator
    Home Point Financial
    8351 North High Street
    Suite 101
    Columbus, OH 43235
    Office:614-721-8604
    Fax:614-448-4571
    NMLS:83286
    Contact Me
    My Website
     
    This Newsletter is for informational purposes only. The information contained herein may not be applicable to every situation or jurisdiction, and we urge you to consult your professional advisor prior to acting on information contained herein. The content, accuracy and opinions expressed herein are not verified or endorsed by the sponsor hereof.

    Thursday, June 30, 2016

    Top 20 Markets for June

    Here They Are: The Top 20 Markets for June

    DAILY REAL ESTATE NEWS | THURSDAY, JUNE 23, 2016

    The overall residential housing market is heating up this summer, but a markets in a few cities across the country are in a league of their own, notes Jonathan Smoke, realtor.com®’s chief economist.

    Read more: Existing-Home Sales at Highest Pace in 9 Years


    Realtor.com®’s research team identified the hottest markets by factoring in which ones had the most views per listing on its website and saw the quickest inventory movement. In these markets, homes are selling 20 to 38 days faster than the rest of the U.S.

    Once again, California dominates this month’s list, but eight other states are also represented (Texas, Colorado, Indiana, Ohio, Michigan, Washington, Massachusetts, and New Hampshire). Seasonality is a big factor in this month’s rankings, Smoke notes.

    “This is a peak time for people to be buying vacation homes in Michigan, because the weather is perfect,” Smoke says. “California markets tend to be fairly consistent—we don’t see huge changes.”

    Source: “America’s 20 Hottest Real Estate Markets for June 2016,” realtor.com® (June 23, 2016)

    Existing-Home Sales at Highest Pace in 9 Years

    Existing-Home Sales at Highest Pace in 9 Years

    DAILY REAL ESTATE NEWS | WEDNESDAY, JUNE 22, 2016

    All major U.S. regions except the Midwest saw an uptick in existing-home sales last month, the National Association of REALTORS® reported Wednesday. As tight inventories continue to plague many markets, the median sales price for all housing types climbed to an all-time high of $239,700 in May — up 4.7 percent from a year earlier — as buyer demand outweighs housing supply.

    Total existing-home sales, which are completed transactions for single-family homes, townhomes, condos, and co-ops, increased 1.8 percent month-over-month to a seasonally adjusted annual rate of 5.53 million in May. Sales are now up 4.5 percent from a year ago and are at the highest annual pace since February 2007. This is the third consecutive month for gains in existing-home sales.

    "This spring's sustained period of ultra-low mortgage rates has certainly been a worthy incentive to buy a home, but the primary driver in the increase in sales is more home owners realizing the equity they've accumulated in recent years and finally deciding to trade up or downsize," says Lawrence Yun, NAR's chief economist. "With first-time buyers still struggling to enter the market, repeat buyers using the proceeds from the sale of their previous home as their down payment are making up the bulk of home purchases right now."

    Yun says sales likely will maintain their current pace throughout the summer, assuming there are no further decreases in job growth that could prompt a pause among repeat buyers.

    Here’s a closer look at how existing-home sales performed in May, according to NAR's latest housing report:

    Home prices: The median existing-home price for all housing types was $239,700 in May, up 4.7 percent from a year ago. That also surpasses the previous peak in median sales prices of $236,300, set last June. Days on the market: Properties spent less time on the market in May, selling, on average, after 32 days. That's below the average time on market a year ago (40 days) and the shortest time since NAR began tracking such data in May 2011. Forty-nine percent of homes sold in May were on the market for less than a month, also the highest percentage since May 2011. Short sales were on the market the longest, at a median of 103 days in May, while foreclosures sold in 51 days. Non-distressed homes took 30 days.Housing inventories: Total housing inventory at the end of May increased 1.4 percent month-over-month to 2.15 million existing homes for sale. That is 5.7 percent lower than a year ago. At the current sales pace, unsold inventory represents a 4.7-month supply.

    "Existing inventory remains subdued throughout much of the country and continues to lag even last year's deficient amount," says Yun. "While new-home construction has thankfully crept higher so far this year, there's still a glaring need for even more, to help alleviate the supply pressures that are severely limiting choices and pushing prices out of reach for plenty of prospective first-time buyers."

    All-cash sales: Buyers paying in cash accounted for 22 percent of all transactions in May, down from 24 percent a year ago. Individual investors account for the biggest bulk of all-cash sales. Investors purchased 13 percent of homes in May, down from 14 percent a year ago.Distressed sales: Foreclosures and short sales dropped to 6 percent of all sales last month, down from 10 percent a year ago. Foreclosures comprised 5 percent of sales in May while short sales represented 1 percent of sales. On average, foreclosures sold for a discount of 12 percent below market value while short sales were discounted 11 percent.

    Regional Snapshot

    Here’s how existing-home sales fared across the country in May:

    Northeast: existing-home sales rose 4.1 percent to an annual rate of 770,000, and are now 11.6 percent above a year ago. Median price: $268,600, which is 0.1 percent below May 2015.Midwest: existing-home sales fell 6.5 percent to an annual rate of 1.3 million in May but are still 3.2 percent higher than a year ago. Median price: $190,000, up 4.8 percent from a year ago.South: existing-home sales rose 4.6 percent to an annual rate of 2.28 million in May and are now 6.5 percent above a year ago. Median price: $211,500, up 5.9 percent from a year ago.West: existing-home sales climbed 5.4 percent to an annual rate of 1.18 million in May but are still 1.7 percent lower than a year ago. Median price: $346,900, which is 7.7 percent above a year ago.

    Source: National Association of REALTORS®

    Wednesday, June 22, 2016

    The Glam Style Guide

    If you think that every day should be a special occasion, the only appropriate gift is jewelry, and there's no point in getting dressed unless you're doing it to the nines, this dazzling decorating style will make you feel right at home. Read on for a crash course in getting a glam furniture and décor look.
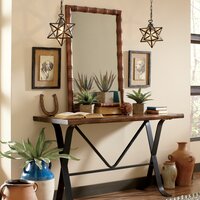
    Glam Style 101: The basics of a high-style space.
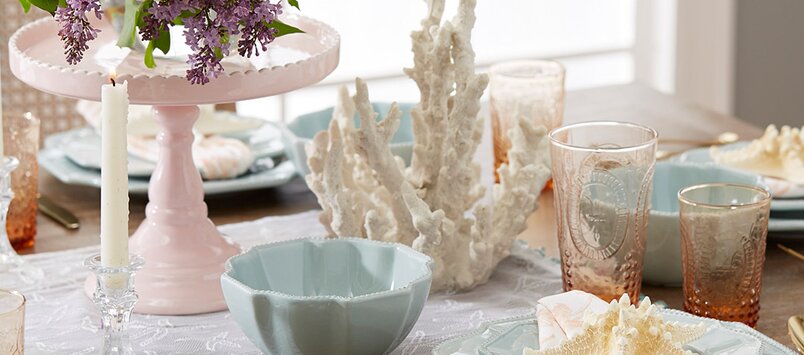
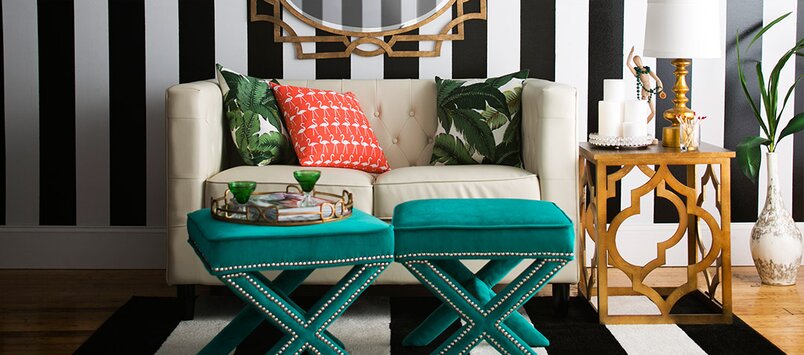
    1. Pile it on: When it comes to decorating a glamorous space, more is more. Build your room around embellished furniture, shimmering accents, and bold color combinations.
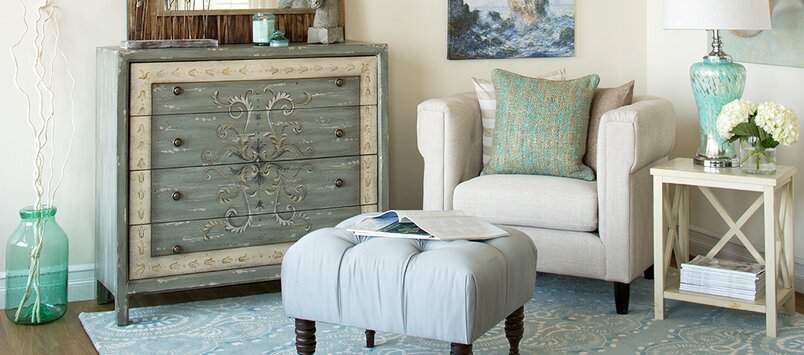
    2. Go Lush and Plush: Furniture and textiles with luxurious texture—like plush velvet sofas, satin sheets, cashmere throw blankets, and flokati rugs—are a staple of the style.
    3. Bring on the Bling: Take inspiration for a lavish look straight from your jewelry box: choose sparkling gem tones, pearlescent finishes, and crystal accents. And don't forget metallics: Incorporate silver and gold tones with chrome light fixtures, brass nailheads, or mirrored furniture.
    4. Add Drama: Each room should have at least one statement-making, show stopping piece. Seek out crystal-laden chandeliers, furniture with exaggerated silhouettes, or an oversized, Art Deco-inspired sunburst mirror.
    Elements of Glam Style: All of the tips you need to bring glamour to your home.
    The Palette: From neutral to saturated, there's a posh palette for every color preference. Here are a few of our favorite pairings for a luxe space.
    Bold and Bejeweled
    For a regal look, base your color scheme around jewel tones. Mix shades of sapphire and turquoise, or pair rich ruby with glimmering gold for a gem of a palette.
    Black, White, and Glamorous
    It doesn't get more dramatic than a room based around classic black and white. Accent this high-contrast pairing with mirrored furniture or metallic silver accents.
    Classically Chic
    Like a perfectly tailored trench coat or little black dress, decor picks in black and camel exude upscale sophistication. To ensure the result is chic, not severe, mix in softer shades of cream and beige, too.
    Glam Furniture
    Incorporating furniture with upscale details and fancy finishes doesn't mean your home can't be comfortable and inviting, too. When decorating a glam room, remember the following to ensure a well-balanced space.
    1. Mix in Mirrored Pieces Create an elevated, but approachable mix by juxtaposing painted pieces or furniture in more traditional wood tones with a mirrored chest, desk, or accent table.
    2. Look for Dressy Details Like jewelry and accessories, tufting, nailheads, and piping are little details with big impact. The more embellishments your furniture has, the more formal the look.
    3. Add in Dramatic Silhouettes Set a chic scene with furniture that features exaggerated proportions or elaborate forms, like arched headboards, high-backed dining chairs, tuxedo sofas, or demilune chests.
    Glam Accents & Decor

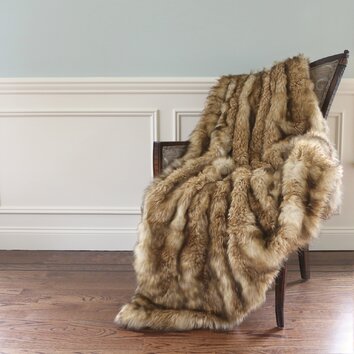
    Faux fur throws are a great way to show off your glam decor sytle.
    A show-stopping space spares no detail. Finish off your design with fanciful flourishes—like faux-fur throws, fashion-forward wall art, and eye-catching lighting — to ensure an elevated room. Opt for a flashy glam wall sconce in gold, black or white to help light up your living room. Read our tips below on how to get the glam out of your home accents and decor:
    1. Go High-Pile: Fur immediately evokes a sense of luxury. Incorporate it at home with a faux sheepskin throw blanket, a Mongolian fur ottoman, or a flokati rug.
    2. Light up the Room: Glam Lighting should be both decorative and functional. Try incorporating a candelabra chandelier, a beaded flush mount, or a pair of sconces with crystal drop shades into your space.
    3. Take Cues from Your Closet: Dress your walls with fashion-inspired prints featuring iconic design houses, or maps of stylish cities like Paris, London, or New York to add panache.
    4. Make the Room Bloom: Whether you choose real blossoms or faux bouquets, flowers are an essential part of glamorous decor. Opt for lush varieties like garden roses, peonies, and hydrangeas.

    https://www.jossandmain.com/Glam-C1860542.html

    Coastal Furniture & Decor Style Guide


    Whether your home has an ocean view or you simply crave a casual, coastal chic feel, there are just a few steps between you and a beach beautiful space. Consider these coastal style furniture ideas and nautical decorating tips.
    Seaside Style 101: The basics of ocean-inspired home design.
    1. Keep it Casual: Since coastal cottages are all about unwinding, furniture and finishes should be relaxed and unfussy. (can we get a quick example that names some furniture types?) e.g. Stay away from wrought iron and go for some weathered wicker patio furniture.
    2. Bring the Outdoors In: The look is inspired by coastal settings, so turn to natural wood tones, natural fibers that evoke beach grass, and colors reminiscent of the sand, sea, and sky. Same as above, e.g. Teak or white dining furniture are favorites for this look.
    3. Let in the Light: As beach house spaces are bright and breezy, plenty of light is a must. To let in lots of natural light, opt for diffusing shades or sheers over windows. Layering light fixtures (like mixing pendants with sconces and table lamps) adds to the airiness.
    4. Think Outside the Shell: A literal approach to coastal style—one that incorporates marine wall decor like anchors, shells, and boats—is more appropriate for harborside homes than inland ones. But even if your home has a water view, limiting yourself to one or two beach-themed patterns keeps the look from crossing into “kitsch”. Beyond those details, focus on using materials and textures that communicate “beach” in a subtle, sophisticated way.
    Elements of Coastal Style: Colors and materials with beach-house charm.
    The Palette: For ocean-inspired homes and beach houses, there’s no combination more classic blue and white. But by varying shades, saturation, and accent colors, you can personalize the palette for your space and style. Whether you prefer nautical and preppy or natural and serene, consider these tips.
    For a New England-nautical vibe
    Accent a navy and white palette with bold pops of red and yellow. For furniture, choose darker, polished wood tones like a walnut coffee table or cherry accent chairs, plus painted pieces in primary shades.
    For a Carolina-coastal approach
    Pair misty blues and pale shades of aqua with softer shades of white like cream and eggshell. With wood, opt for bleached or white-washed finishes.
    For a neutral take
    If you prefer to decorate without much color, evoke a beach house feel by pairing shades of white, gray, and sand with furniture in weathered or reclaimed wood.
    For a tropical twist
    Deep aquamarine shades accented by touches of pink recalls waves, conch, and coral. Painted or natural, pieces like rattan decorative boxes and bamboo framed mirrors augment the island vibe.
    The Furniture
    1. Say yes to slipcovers. Casually chic and easy to clean, slipcovered seating in a pale neutrals evokes the sails of a boat.
    2. Choose furniture with function. Bunk beds, daybeds with trundles, pullout sofas, and extra seating make it easy to accommodate house guests.
    3. Follow tradition.Coastal style has traditional roots, so look for timeless shapes or antique pieces. If you want a more updated look, paint classic furniture white or a vibrant shade of red or blue.
    The Accents & Decor
    1. Include elements of the coastal life. Stripes, rope accents, porthole mirrors, and buoys add classic regatta-inspired charm. Sea glass, sun-bleached shells, and collections of glass bottles in various shades of blue and green are reminders of the ocean landscape.
    2. Bring in blooms. Bouquets of real or faux hydrangeas, pale roses, and tulips keep the look light. Choose casual arrangements, and stick to a mellow pastel palette.
    3. Incorporate details found in classic coastal homes. Beadboard, shiplap, and wainscoting add interest to walls. Lantern-style pendants illuminate interiors and outdoor spaces alike.

    https://www.jossandmain.com/Coastal-C1860520.html